Fiat Off-Ramps in 2026: Why Selling Crypto Can Be Harder Than Buying It
- The Off-Ramp Is More Than a Withdraw Button
- Why the Return Journey Receives More Attention
- Payment Methods: Similar Goal, Different Experience
- Limits Are Often Discovered at the Worst Moment
- Source of Funds: What a Bank May Want to See
- The Final Amount Can Be Lower Than Expected
- Stablecoins Solve One Problem, Not All of Them
- P2P Can Be Helpful, but It Changes the Risk Profile
- A Practical Preparation Checklist
- Conclusion
- FAQ
- Sources
- Need Help?
Buying digital assets has become a familiar online action. A card payment, a bank transfer, or an in-app purchase can place Bitcoin, Ether, or stablecoins in an account within minutes. The route in the opposite direction is less predictable. Converting a portfolio into money that arrives safely in a personal account can involve several institutions, each with its own checks and timelines.
This difference matters most when a user needs liquidity quickly. The trade itself may settle almost immediately, yet the payment can remain pending because the transaction has moved beyond the exchange and into the banking system. In 2026, the difficult part is often not selling the asset. It is proving, routing, and receiving the proceeds.
The Off-Ramp Is More Than a Withdraw Button
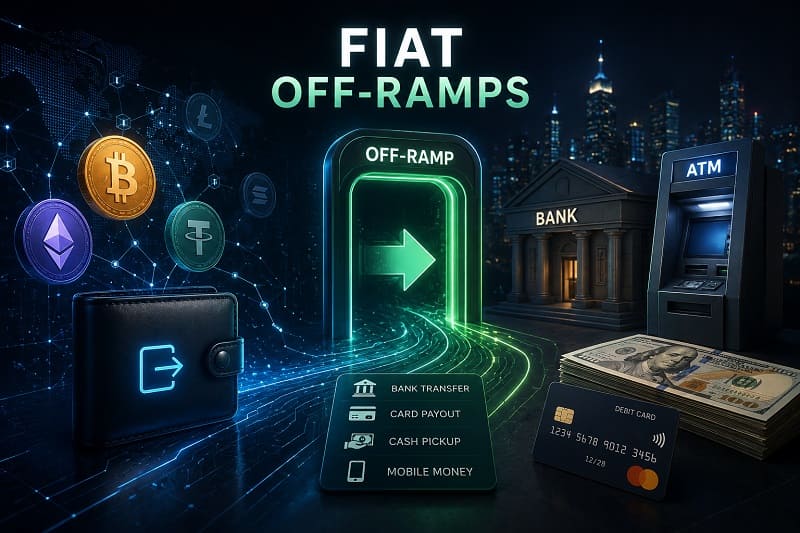
A fiat off-ramp is the process that connects a digital-asset balance with traditional money. It may end in a bank account, a debit card, or an approved electronic-money service, but the underlying process is broadly similar: an asset is sold, a fiat balance is created, and a payment provider sends that balance through a banking rail.
The first stage is market activity. The second is a payment event. They are governed by different systems.
A typical sequence looks like this:
- The customer transfers coins to a trading venue or uses assets already held there.
- The asset is exchanged for a supported currency.
- The customer selects a destination and payment method.
- The platform runs security, identity, and transaction checks.
- A banking partner processes the payment.
- The receiving institution decides whether it can credit the funds without further questions.
This explains why blockchain speed does not determine the final arrival time. A transfer on-chain may be confirmed in minutes, while the corresponding fiat payment can take longer because it travels through SEPA, ACH, SWIFT, Faster Payments, or another regulated network. Kraken’s current withdrawal guide shows how timing, minimums, and costs vary by route rather than by the crypto asset being sold.
Why the Return Journey Receives More Attention
Banks do not automatically treat every incoming payment from a recognised exchange as problematic. However, they are expected to understand customer behaviour and investigate activity that appears unusual, inconsistent, or difficult to explain.
A person who normally receives a salary and pays household bills may attract questions after receiving a large transfer linked to a trading platform. The question is not necessarily whether cryptocurrency is allowed. The institution may simply need to establish where the original funds came from and whether the transaction fits the customer’s profile.
FinCEN’s guidance describes how businesses that administer or exchange convertible virtual currency can fall within anti-money-laundering obligations, while the FCA continues to frame cryptoasset activity around consumer protection, financial-crime controls, and appropriate registration.
Common triggers for extra scrutiny include:
- a high-value payment that differs from previous account activity;
- a newly added beneficiary account;
- an account name that does not match the destination account;
- incomplete identity checks;
- a rapid change in transaction volume;
- a payment involving several intermediary services;
- recent deposits that have not fully cleared;
- inconsistent or missing evidence about the origin of the assets.
A review is not proof of misconduct. It is often an operational consequence of moving value from a pseudonymous blockchain environment into an account-based financial system.
Also Read: KYC Verification or Trap? How Scammers Exploit Crypto Exchange Users in 2026
Payment Methods: Similar Goal, Different Experience
| Method | Where It Is Commonly Used | Expected Timing | Main Consideration |
|---|---|---|---|
| SEPA transfer | EUR payments within supported European banking networks | Same day to two business days | Requires compatible account details and regional availability |
| Faster Payments | GBP transfers in the United Kingdom | Often same day | Depends on platform support and the receiving bank |
| ACH | USD transfers in the United States | Usually several business days | Settlement and security rules can affect availability |
| SWIFT | International payments in major currencies | One to five business days | Correspondent banks may add delays or deductions |
| Instant card or bank payout | Selected countries and eligible accounts | Minutes to 24 hours | Often subject to lower limits and provider approval |
The same platform may offer very different options depending on the user’s country. A European customer may have access to an inexpensive euro transfer, while another customer may need to use an international wire. A platform can also support a currency for trading without offering a convenient payout route for that currency.
Coinbase’s official cash-out instructions make this distinction clear: users choose a currency and destination, review the payment details, and then confirm the transfer. Its instant cash-out guidance also notes that availability and transaction limits depend on the selected method.
Limits Are Often Discovered at the Worst Moment
A user can hold or sell a substantial amount without being able to move the full fiat balance in one payment. Trading access and payment access are not always identical.
Restrictions may arise from the account’s verification level, the chosen transfer route, the age of the account, recent funding activity, or the receiving bank’s own controls.
| Restriction | What It Affects | Practical Response |
|---|---|---|
| Verification tier | Maximum value available for payments | Complete identity or address checks before a large sale |
| Method-specific cap | Amount permitted through a card, local transfer, or wire | Compare available payment rails before converting assets |
| Security hold | Temporary restriction after certain purchases or deposits | Check the hold period rather than placing repeated requests |
| New-account controls | Access to higher-value transfers | Build a normal account history and retain documentation |
| Receiving-bank review | Whether the incoming payment is credited immediately | Prepare a concise source-of-funds explanation |
For example, Kraken states that certain funding methods can trigger temporary restrictions. Its published guidance says that some card, digital-wallet, PayPal, and ACH transactions may result in a 72-hour hold, while ACH Plaid deposits can be held for seven days before funds become available for withdrawal.
The important point is not to assume that a delay means a platform has failed. In many cases, the restriction is disclosed in advance but overlooked until the customer needs immediate access to money.
Source of Funds: What a Bank May Want to See
A well-documented transaction history can make a significant difference when a payment is reviewed. The bank may want to understand how the customer acquired the assets, where they were held, how they were sold, and why the amount is arriving now.
Useful evidence may include:
- account statements from the exchange;
- deposit and withdrawal history;
- trade confirmations;
- wallet addresses and transaction hashes;
- screenshots or exports showing transfers between personal wallets;
- proof of the original purchase;
- tax records, where relevant;
- a brief written explanation that connects the documents in chronological order.
The strongest evidence is not necessarily the longest file. It is the clearest one. A statement showing a fiat deposit, the purchase of an asset, the later sale, and the outgoing bank payment is easier to review than a folder of disconnected screenshots.
It is also wise to avoid artificial transaction splitting. Breaking a large payment into smaller pieces solely to evade controls can create a more confusing pattern and may increase compliance concerns.
Also Read: Bybit Withdrawal Delays: Temporary Security Measure or Bigger Problem?
The Final Amount Can Be Lower Than Expected
The visible trading fee is only one element of the total cost. A user may pay for moving coins to the exchange, converting them, transferring fiat, and changing currencies before the money reaches the destination.
| Cost Element | When It Applies | Why It Is Easy to Miss |
|---|---|---|
| Blockchain network fee | When assets are sent to a trading platform | It depends on the network rather than the eventual fiat payment |
| Trading commission | When an order is executed | It may differ between simple conversion and advanced trading tools |
| Spread | During instant conversion | It can be embedded in the quoted price |
| Platform payment fee | When fiat leaves the account | It varies by currency and transfer method |
| Foreign-exchange conversion | When the payout currency differs from the receiving account | The bank or provider may apply its own rate |
| Correspondent-bank deduction | During some international wires | It may appear only after the payment is sent |
Before confirming a transfer, users should review the final payment screen, not just the exchange’s headline fee schedule. Coinbase’s own instructions direct customers to preview the withdrawal details and fees before submitting the request.
Stablecoins Solve One Problem, Not All of Them
Stablecoins can reduce price volatility while a person decides when to sell. They do not remove the need to use a regulated payment route.
USDT or USDC may be convenient for moving value between wallets and platforms, but a bank cannot normally receive those tokens as a standard account credit. They must first be exchanged into fiat, after which the same verification, payment, and bank-review questions remain.
This distinction is particularly important for users who believe that holding a dollar-pegged token is equivalent to holding dollars in a bank. The price reference may be similar; the legal and operational route is not.
P2P Can Be Helpful, but It Changes the Risk Profile
Peer-to-peer trading is often used where direct banking options are limited. It can offer flexibility, but it may also complicate the paper trail.
Risks include payments from unknown third parties, fake transfer confirmations, payment reversals, and a bank statement filled with unrelated incoming transfers. These patterns can be harder to explain than one payment from a verified exchange account.
P2P activity is not automatically suspicious or improper. However, users should keep clear records, use established platform protections where available, and avoid sending funds before independently confirming payment receipt.
A Practical Preparation Checklist
Before converting a meaningful balance, it is worth taking a few steps:
- Check whether the platform supports your residence, currency, and preferred payment method.
- Verify that the account holder’s name matches the bank-account name.
- Complete identity verification before initiating a large transaction.
- Save trade history, deposit records, and wallet transaction details.
- Review whether recent purchases are subject to a temporary hold.
- Make a small test payment if you have never used the destination account.
- Calculate the entire route, including network, trading, transfer, and foreign-exchange costs.
- Contact the bank in advance if the expected payment is unusually large.
- Use only official support channels if a transfer is delayed.
- Ignore anyone who asks for an extra crypto payment to “release” funds.
That final warning is especially important. Legitimate fees are normally shown in the platform interface or explained through official support. A request to send assets to an unfamiliar wallet to unlock a payment is a serious red flag.
Conclusion
The difficulty of turning crypto into usable bank money is not a technical failure. It reflects the point where a fast, global blockchain transaction meets slower and more regulated financial infrastructure.
The best preparation is simple: choose the destination before selling, understand the available rails, keep records from the beginning, and allow time for reviews. A purchase may take seconds. Bringing the proceeds back into the banking system requires a more deliberate plan.
FAQ
What is a fiat off-ramp?
It is a service or process that converts digital assets into traditional currency and sends that money to a bank account, card, or another approved payment destination.
Why has my payment not arrived yet?
The delay may come from a platform security hold, bank processing time, verification requirements, or a review by the receiving institution.
Can a bank ask where my crypto proceeds came from?
Yes. A bank may request records showing the origin of the funds, the transaction history, and the sale that produced the payment.
Is selling crypto the same as withdrawing money?
No. Selling creates a fiat balance on a platform. A separate payment request is needed to move that balance to a bank or other destination.
Are stablecoins easier to cash out?
They can make it easier to hold a stable value before selling, but they still need to be converted into fiat through a supported service.
Why is a transfer limit lower than my trading limit?
Platforms often apply different controls to market activity and external payments.
Is SEPA always cheaper than SWIFT?
It can be less expensive for eligible euro transfers, but the final cost depends on the platform, bank, payment route, and currency conversion.
Should I use another person’s bank account?
Usually not. Many providers require the destination account to be held in the same name as the verified customer.
Is a small test payment useful?
Yes. It can confirm that the account details, timing, and payment route work as expected before a larger transfer.
Sources
- FinCEN — Convertible Virtual Currency Guidance
- Financial Conduct Authority — Cryptoassets Information
- FCA — Fiat-to-Crypto and Crypto-to-Fiat Ramp Services
- Kraken — Cash Withdrawal Options, Fees and Processing Times
- Kraken — Cash Deposit and Withdrawal Holds
- Coinbase — Cash Out Available Balance
- Coinbase — Instant Cashouts
- Coinbase — USD ACH Withdrawals
Need Help?
If you're stuck unable to withdraw your crypto holdings into fiat currency — facing endless KYC loops, sudden withdrawal limits, frozen funds, or an exchange that simply won't process your bank transfer — you can request a free consultation with StockView specialists.
An expert review can help assess whether your situation involves legitimate compliance hurdles or intentional stalling tactics by a fraudulent platform, and evaluate realistic options for recovering your money, including payment disputes, banking channel interventions, and alternative off-ramp strategies.
Get professional help with your case.